Professional Forex Trading Framework Guidelines: Build Rules You Can Test
Turn your forex strategy into a testable framework for risk, trade selection, execution, review, and prop firm rule compliance.
A professional forex trading framework converts your strategy into rules for selecting, sizing, managing, and reviewing trades. Start with the core risk formula: position size equals permitted dollar loss divided by stop distance and pip value. No risk percentage or reward target is universally optimal, so define your personal and account-level loss limits before choosing entry signals.
No time to read?
- A strategy identifies opportunities; a framework also controls risk, execution, review, and when not to trade.
- Risk per trade should be derived from tested drawdown tolerance and account restrictions, not copied from a universal percentage.
- A stop defines invalidation and makes position sizing possible, but gaps and slippage can still produce a larger loss.
- The framework should be tested in simulation, measured by regime, and revised only from recorded evidence.
A framework is the operating system around your strategy
A strategy describes how you seek an edge in the market. A setup is a specific configuration that may express that edge. An indicator processes market data, while a signal identifies a possible action. None of these, by itself, tells you whether you are allowed to trade, how much you may risk, or when poor conditions require you to stop.
A professional forex trading framework is the rules-based operating system surrounding those components. Useful professional forex trading framework guidelines should govern:
- Which currency pairs and trading sessions are eligible
- How market structure and the market regime are classified
- What qualifies as an entry and where the trade becomes invalid
- How position size, leverage, and total exposure are controlled
- How open positions are managed and exited
- How results and rule adherence are recorded
- Which drawdown threshold suspends trading
These decisions form your forex risk management rules. Their purpose is not to predict every move in the forex market. It is to make execution repeatable, disciplined, survivable, and testable.
This distinction matters because discretionary trading does not have to mean improvisation. You can exercise judgment within predefined boundaries, such as accepting price action trading setups only when the higher timeframe structure, liquidity, and volatility regime align. Consistency then produces data that can be evaluated. Random execution does not.
Set the loss budget before looking for an entry
Risk begins at the account level, not at the entry candle. Define the maximum permitted loss per trade, the maximum combined exposure across open positions, and the loss level that ends the session or suspends the framework.
The often-cited 2% risk cap should be treated as a ceiling to evaluate, not as a universal professional standard. A trader facing a tight drawdown threshold may need materially less risk. Professional environments generally prioritize drawdown control and survival over short bursts of return.
Fixed fractional risk calculates the permitted loss as a percentage of current account equity:
Permitted dollar loss = account equity × risk percentage
The basic forex position sizing formula is:
Position size = permitted dollar loss ÷ (stop distance in pips × pip value per lot)
The stop must come from structural invalidation, not from the position size you want. If a valid stop is farther away, position size must decrease. Volatility-adjusted position sizing applies the same principle when volatility expansion requires wider stops. During volatility compression, a mechanically tight stop may still be inappropriate if a breakout is likely.
Correlation limits are also necessary. Long EUR/USD and short USD/CHF positions, for example, may create overlapping U.S. dollar exposure. Each trade can appear compliant in isolation while the combined scenario risk exceeds the account budget.
Position Size Calculator
function calculateFxSize() {
const equity = Number(document.getElementById(‘fx-equity’).value);
const riskPercent = Number(document.getElementById(‘fx-risk-percent’).value);
const stopPips = Number(document.getElementById(‘fx-stop-pips’).value);
const pipValue = Number(document.getElementById(‘fx-pip-value’).value);
const output = document.getElementById(‘fx-result’);
if (!(equity > 0) || !(riskPercent > 0) || !(stopPips > 0) || !(pipValue > 0)) {
output.textContent = ‘Enter positive values in every field.’;
return;
}
const permittedLoss = equity * riskPercent / 100;
const positionSize = permittedLoss / (stopPips * pipValue);
output.textContent =
‘Permitted loss: $’ + permittedLoss.toFixed(2) +
‘. Calculated position size: ‘ + positionSize.toFixed(4) +
‘ lots. Confirm contract specifications and pip value with your platform before trading.’;
}
The calculator provides a sizing result, not permission to enter. You must still account for spread, commission, slippage, gaps, correlated exposure, and any stricter account rule.
Match the framework to your trading style and temperament
Your forex trading plan must fit your available time, tolerance for drawdown, and need for discretion. A framework that conflicts with your schedule will eventually encourage missed entries, rushed decisions, or rule changes made under pressure.
| Framework | Decision frequency | Screen time | Overnight exposure | Execution demands | Typical emotional pressure |
|---|---|---|---|---|---|
| Rule-based discretionary | Variable | Moderate to high | Depends on holding period | Requires consistent judgment within written filters | Doubt and selective rule interpretation |
| Fully systematic | Set by the system | Low to moderate after implementation | Depends on system design | Requires accurate automation or disciplined signal execution | Intervening after losses or overriding signals |
| Scalping | High | High and concentrated | Usually limited | Sensitive to spread, latency, liquidity, and slippage | Rapid decisions and temptation to revenge trade |
| Day trading | Moderate | Concentrated by session | Usually avoided | Requires session discipline and timely execution | Overtrading during inactive periods |
| Swing trading | Lower | Lower, with periodic review | Common | Requires gap and news risk planning | Holding through adverse movement |
Scalping may suit a trader who can monitor live market conditions and execute without hesitation. Day trading offers fewer overnight variables but still demands scheduled screen time. Swing trading reduces decision frequency while introducing overnight and weekend exposure.
A systematic model can reduce moment-to-moment discretion, but it does not eliminate emotional pressure during drawdown periods. A rule-based discretionary model offers flexibility during market regime changes, although its judgments must be documented precisely enough to test.
Choose the lowest-complexity model you can execute consistently. Scalability and long-term consistency come from fit, not from copying another trader’s preferred timeframe.
Use a decision tree to reject weak setups
A high-probability setup is not a certainty. It is a configuration that satisfies filters associated with favorable historical expectancy. The decision tree should therefore reject trades before it tries to justify them.
Apply the sequence in order:
- Eligible market: Is the currency pair included in the written framework?
- Session: Is the relevant market open, with acceptable liquidity and execution quality?
- Market regime: Is price trending, ranging, compressing, or entering volatility expansion?
- Directional context: Do higher and lower timeframes support trend, range, or permitted counter-trend trading?
- Scheduled event risk: Is a central bank release or economic announcement close enough to invalidate normal assumptions about spread, slippage, or volatility?
- Market structure: Are higher highs, lower lows, support, resistance, or range boundaries defined objectively?
- Entry trigger: Has the required price action, candlestick pattern, or other signal actually completed?
- Stop location: Is there a logical structural invalidation point?
- Projected reward: Does the target satisfy the tested risk-reward ratio after allowing for trading costs?
- Existing exposure: Would the position breach account risk or correlation limits?
- Execution check: Are spread and liquidity acceptable at the moment of entry?
Classify conditions as non-negotiable or contextual. A contextual factor may add confluence, but failure of any non-negotiable condition means no trade. Do not compensate for weak liquidity with a stronger candle pattern or ignore scheduled news because the target looks attractive.
Scenario planning should cover at least three paths: price triggers the entry and follows through, price triggers and immediately invalidates the setup, or price never triggers. The third outcome requires no action. Avoiding low-quality trades is part of execution, not inactivity.
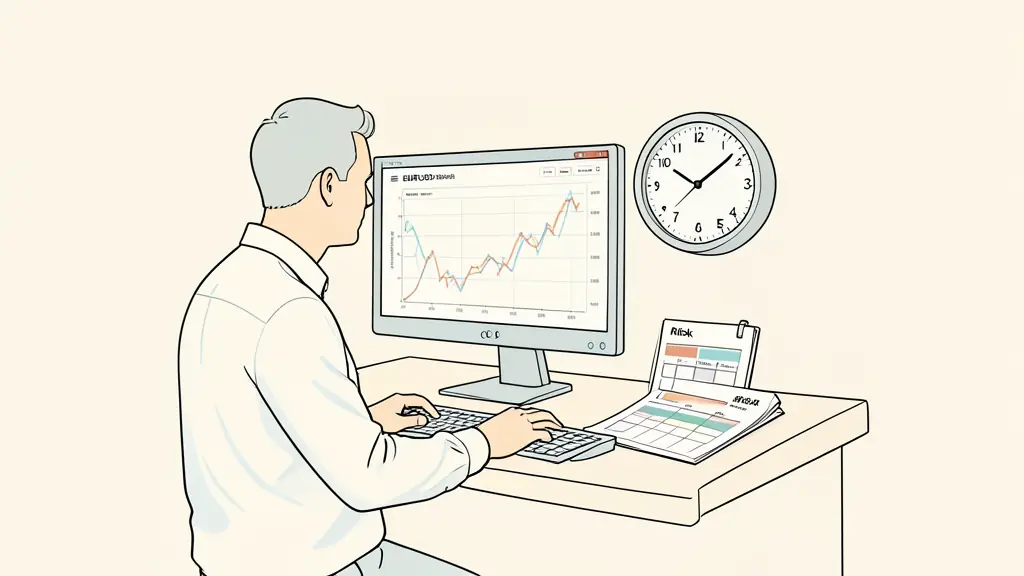
One trade from market context to recorded outcome
The following EUR/USD day trade is hypothetical. Symbols are used instead of fabricated market prices:
Ris the fixed dollar risk.Dis the distance in pips from entry to structural invalidation.Vis the dollar value of one pip for one lot.
Context and qualification
Suppose the higher timeframe shows rising market structure, while the execution timeframe has pulled back without breaking the prior structural low. Liquidity is acceptable, no prohibited scheduled announcement conflicts with the holding window, and price action produces the framework’s required bullish trigger.
The stop belongs below the structural invalidation point. Its distance is D pips. Position size is therefore:
Position size = R ÷ (D × V)
If volatility requires a wider stop, D increases and the position becomes smaller. Moving the stop closer solely to obtain a larger position would reverse the correct process.
Entry and target
The trade is entered only after the trigger completes. If the framework requires a 1:2 planned reward-to-risk relationship, the target must be at least 2D pips from entry before costs. If market structure places a realistic resistance objective inside that distance, the trade is rejected rather than forced into compliance.
The management plan is fixed before entry. The stop cannot be widened. A trailing stop may be used only if its activation rule was defined and tested in advance.
Winning outcome
Price reaches the target without violating the management rules. The gross recorded result is +2R. The journal should also include the market regime, entry evidence, spread and costs, execution difference, management actions, and whether every rule was followed.
Stopped-out outcome
Price falls to structural invalidation and the stop closes the position. The planned result is -R, subject to possible slippage. This is not evidence that the framework failed. It is a normal outcome of a probabilistic process.
The same professional trading rules apply to both outcomes. A compliant loss can be better evidence of process quality than a profitable trade taken outside the framework. Record both without changing the setup definition after seeing the result.
Reward-to-risk only matters alongside win rate and execution
Planned reward-to-risk compares the intended profit with the predefined loss. Realized reward-to-risk measures what actually happened after early exits, slippage, spreads, commissions, trailing stops, and execution errors.
A 1:2 target is not automatically superior to 1:1. Before costs, the break-even win rate is:
Break-even win rate = average loss ÷ (average win + average loss)
For a 1:2 model:
1 ÷ (2 + 1) = 33.3%
For a 1:1 model:
1 ÷ (1 + 1) = 50%
Trading costs raise both thresholds. They can have a particularly strong effect on short-duration strategies with small price targets.
An expectancy model combines win rate, average realized win, average realized loss, and costs:
Expectancy = (win probability × average win) - (loss probability × average loss) - average costs
A trader can plan 1:2 but realize less if profitable positions are repeatedly closed early. Conversely, a tested 1:1 framework can have positive expectancy if its win rate and execution quality compensate for the smaller average win.
The appropriate threshold must come from recorded results for the specific setup, session, and volatility regime. Prediction is less important than whether the process produces a positive expectancy after realistic costs.
Non-negotiable controls prevent a normal loss from escalating
A predefined stop loss defines invalidation and makes position sizing possible. It cannot guarantee the exact loss because gaps and slippage may produce a worse fill, but trading without one leaves the account exposed to an undefined outcome.
Your rules-based operating system should explicitly prohibit:
- Widening a stop loss because price is approaching it
- Martingale sizing, where exposure increases after a loss in an attempt to recover
- Revenge trading after a stopped-out position
- Unplanned averaging down into an invalidated setup
- Excessive leverage that turns normal price movement into account-threatening exposure
- Opening several correlated positions without measuring combined risk
- Switching strategies immediately after a short losing sequence
- Trading low-liquidity periods that fall outside the tested framework
Leverage magnifies both gains and mistakes. Control it through stop-based position sizing and aggregate exposure limits, not through confidence in a signal.
A losing sequence should activate the predefined drawdown threshold and review process. It should not trigger larger positions or looser standards. Survival is more important than a rapid recovery attempt.
Build, test, and revise the framework as a controlled process
A framework becomes useful only when its rules can be observed, tested, and revised without hindsight. Build it through a controlled workflow:
- Write testable rules. Define eligible markets, sessions, regimes, setup criteria, entry and exit logic, stop placement, position sizing, correlation limits, and suspension conditions.
- Replay or backtest. Apply the same definitions to historical data without rewriting them to fit each chart.
- Run a demo forward test. Execute under current market conditions using a demo environment on a suitable trading platform, such as MetaTrader 4, MetaTrader 5, or WebTrader where available.
- Journal every decision. The trade journal should include eligible setups taken, eligible setups missed, and rejected setups. Rejections reveal whether filters are useful or merely restrictive.
- Evaluate performance. Measure expectancy, maximum observed drawdown, average realized reward-to-risk, rule adherence, execution costs, and results by market regime.
- Refine deliberately. Change one defined component at a time, then test it again before adoption.
Record volatility compression, volatility expansion, trending conditions, ranges, and breakout environments separately. An apparently profitable aggregate result can hide poor performance in one regime and dependence on another.
Revision requires sufficient recorded evidence or a structural change in live market conditions. One loss is not evidence. One large winner is not validation. If results deteriorate, first distinguish between normal variance, rule-breaking, higher costs, and genuine regime change.
Consistency comes from structure, but flexibility still matters. The goal is not an unchangeable system. It is a controlled method for testing and refining changes without strategy hopping.
Add a prop firm rule layer before trading the same system
A framework that is acceptable in a personal account may fail under prop firm rules. Before purchasing an evaluation, understand how prop firm evaluations, drawdowns, and funded accounts work, then add the firm’s current restrictions as a separate risk layer.
Check at least:
- The daily loss limit and how equity, balance, floating losses, and trading costs affect it
- Whether maximum drawdown is static, relative, or trailing
- The time and time zone used for daily limit resets
- Consistency rules that restrict how much profit can come from one day or trade
- Restrictions around economic announcements and central bank releases
- Weekend and overnight holding rules
- Limits on robots, trade copying, or particular execution practices
- Minimum trading requirements and payout conditions
- Rules governing scaling, withdrawals, and account closure
Calculate permitted risk from the nearest applicable failure threshold, not from the advertised account size. If the remaining daily loss allowance is closer than the maximum drawdown limit, the daily allowance controls. Open losses and correlated exposure must be included before another position is added.
Tight limits may require lower fixed fractional risk, fewer simultaneous trades, or different execution around news. They may also make a strategy unsuitable even if it has positive expectancy in an unrestricted account.
Verify current official terms before paying for or trading an evaluation. Rules, platforms, and service providers can change, and no framework guarantees that you will pass an evaluation, receive funding, or qualify for a payout.
Write one framework, calculate its risk limits, define its setup decision tree, and test it in simulation before using it live. Trading forex and prop firm evaluations involve substantial risk, including the loss of trading capital or evaluation fees. This material is educational, not personalized financial advice. Consult a qualified financial professional where appropriate.
This article does not replace advice from a qualified professional: consult a specialist about your own situation.
Risk warning. Trading involves a risk of losing capital. Prop firm challenges are paid and passing them is not guaranteed. This content is for information only and is not investment advice.
Orva Massé teste et compare les prop firms afin d’aider les traders à choisir des partenaires fiables et adaptés à leurs objectifs. Avec une approche claire et pragmatique, Orva décrypte les règles d’évaluation, les frais et les conditions de retrait.
Want to go further?
Leave your email and we'll let you know when a new article is out.